Gov. Kathy Hochul will join the federal school-choice scholarship tax credit starting Jan. 1, 2027, despite a union campaign to reject it.
What comes next is SGO setup, state filing, and a continued repeal fight. The program is the federal Education Freedom/Federal Scholarship Tax Credit. It gives a dollar-for-dollar federal tax credit for cash gifts to approved scholarship-granting organizations, called SGOs, which then pay eligible education costs.
Table of Contents
- What Hochul decided
- Why unions fought the opt-in
- How the tax credit works
- What must happen before scholarships flow
- What the ongoing fight means
What Hochul decided
Hochul announced Oct. 9, 2026, that New York will participate beginning Jan. 1, 2027.
Chalkbeat reported the move as a direct rejection of union pressure to opt out in Hochul opt-in report. Hochul said New York would participate "if, and only if" public-school students benefit. She claimed millions in additional aid without taking "a single dollar" from public schools or state and local budgets.
Why unions fought the opt-in
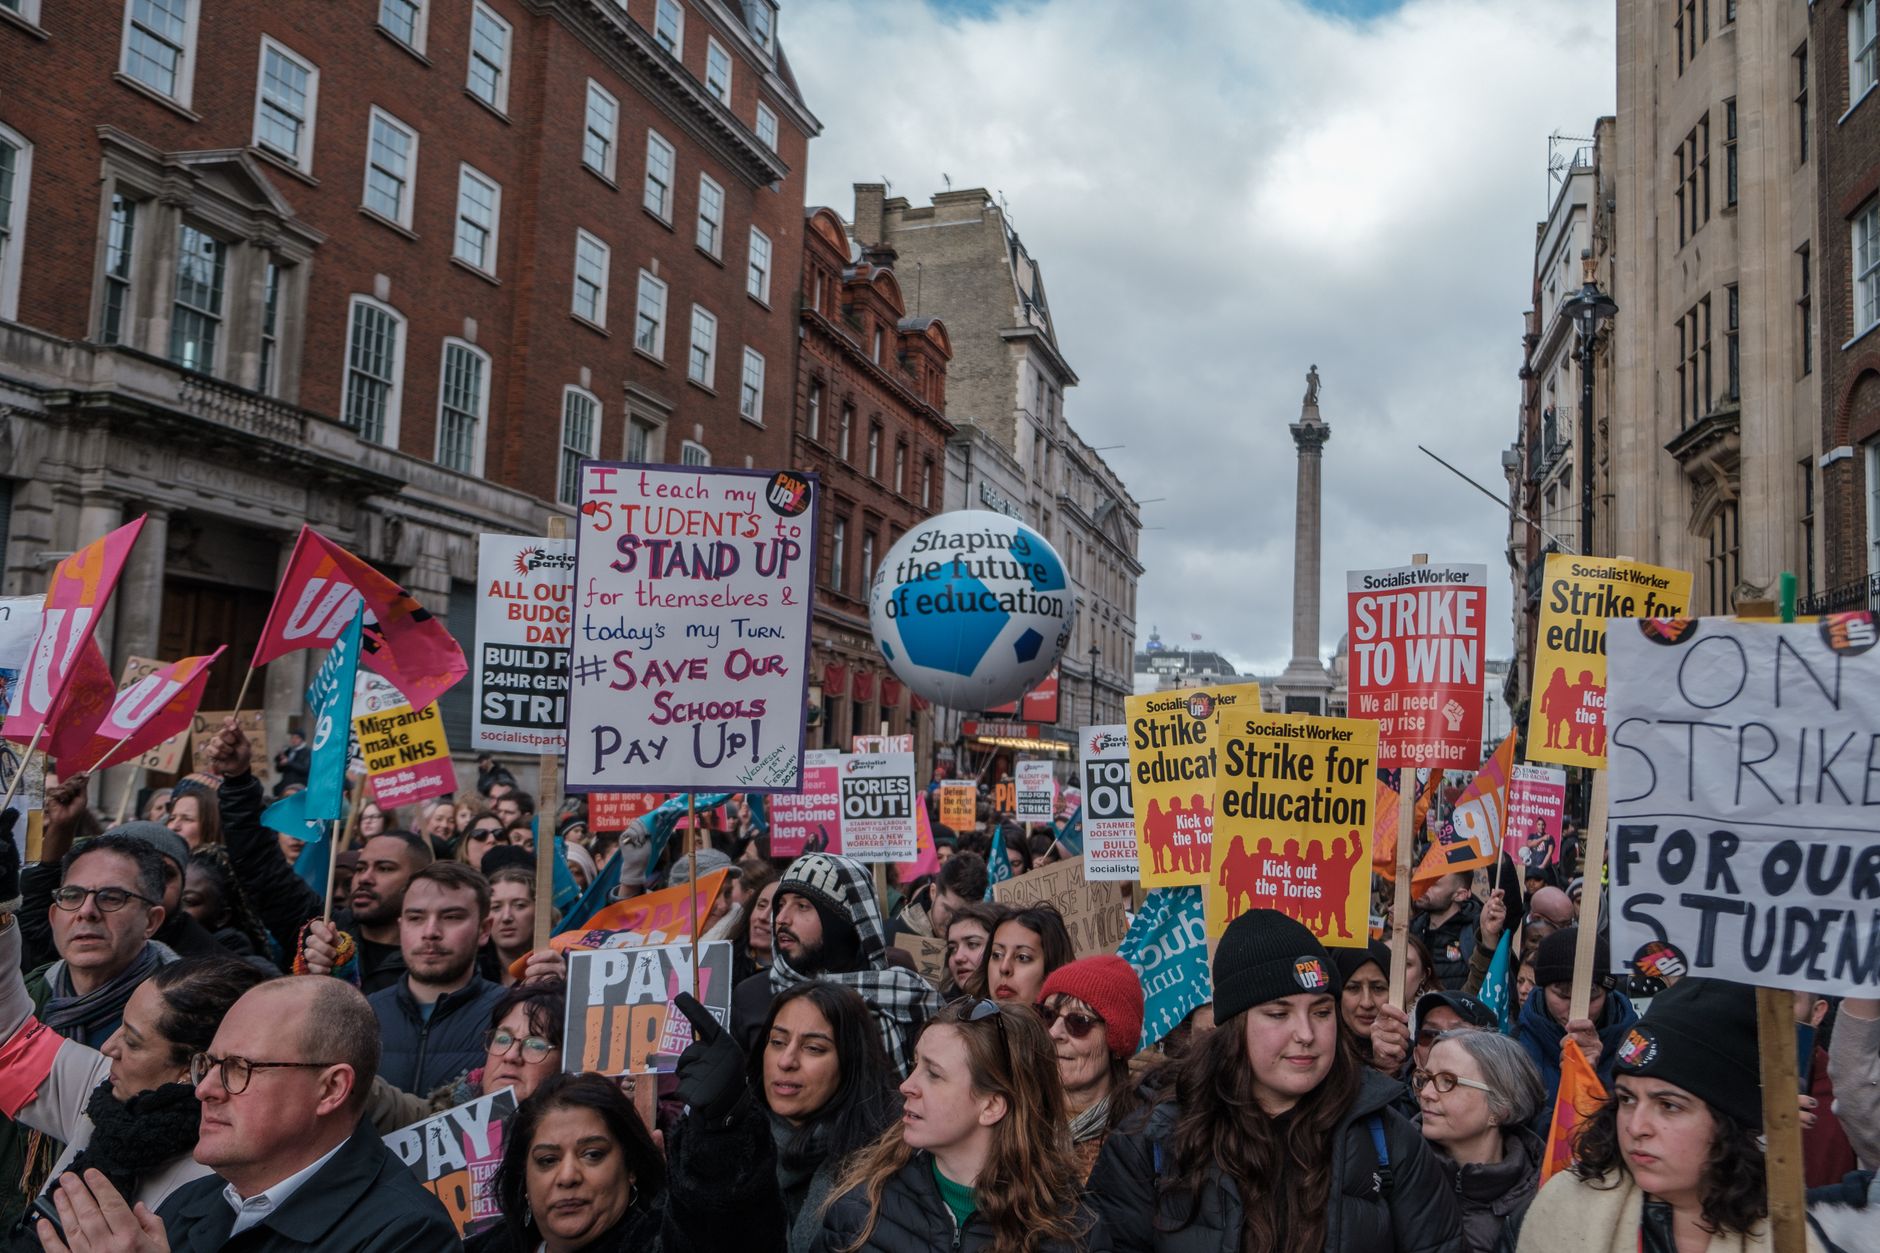
NYSUT, New York City's UFT and national affiliate AFT pressed Hochul to refuse participation. Chalkbeat described their September Manhattan rally, coalition petition and letter-writing drive warning the program threatens public education in union opt-out drive.
NYSUT President Melinda Person said Oct. 1 final regulations contain "poison pills." She said they bar New York from setting SGO standards, choosing participants, or limiting eligible schools and expenses.
How the tax credit works
The program was created by the July 2025 federal tax law as IRC Section 25F/ECCA. It offers individuals a nonrefundable dollar-for-dollar federal credit up to $1,700, or $3,400 for joint filers, for cash gifts to approved SGOs.
📨 Get Free Accountability Coverage Alerts
Free · No spam · Unsubscribe anytime
Only students in a governor-opted-in "covered state" can receive scholarships. Education Week explained that taxpayers in any state can still claim the credit by donating to an SGO serving a participating state in federal tax-credit rules. For readers, the split matters:.
- New York students can receive scholarships only if New York completes opt-in.
- A donor living outside New York can support a New York-serving SGO.
- The credit is nonrefundable, so it can reduce tax owed but not create a refund beyond that limit.
What must happen before scholarships flow
For 2027 coverage, Treasury and IRS temporary rules require an advance state election by Jan. 1, 2027. They also require an IRS SGO list by Feb. 15, 2027.
Hochul's announcement did not confirm New York had filed the election. That filing is the practical step that turns the announcement into student eligibility. Once SGOs qualify, they can fund private tuition and public-student tutoring, technology and after-school costs. Total awards operate under a $10 billion annual federal cap.
What the ongoing fight means
NYSUT vows repeal work, and legislative leaders oppose opt-in. That means eligibility rules, SGO oversight, and eligible expenses may face new bills or federal changes.
Families and donors should watch the state election filing and the Feb. 15 IRS SGO list. Those two actions decide when New York students can apply and where donors can give.
You Might Also Like
- Why Does Trump Call UAW Leader Shawn Fain a Threat to His Agenda?
- UAW’s Shawn Fain Declares Win Over Trump-Era Labor Fight — What’s Next?
- Why Trump Tariffs and Retail Consumer Claims Is Back in Federal Court